
Purchase documents
First the supplier's record (Operations › Structure › Suppliers), with their bank and their 20-digit RIB, or their IBAN if they are abroad. Then their documents: a purchase order becomes a receipt, then a purchase invoice; a purchase credit note corrects it. Only a validated purchase invoice can be paid.
The payment order
New payment: the type (supplier settlement, foreign settlement, supplier advance, unpaid settlement or disbursement), the method (transfer, bill of exchange, cheque or bank card; none is chosen in advance), the invoices settled and, where it applies, the withholding tax. Validate issues the order, numbered OP260001, OP260002…: the invoice is settled and the withholding certificate is created.
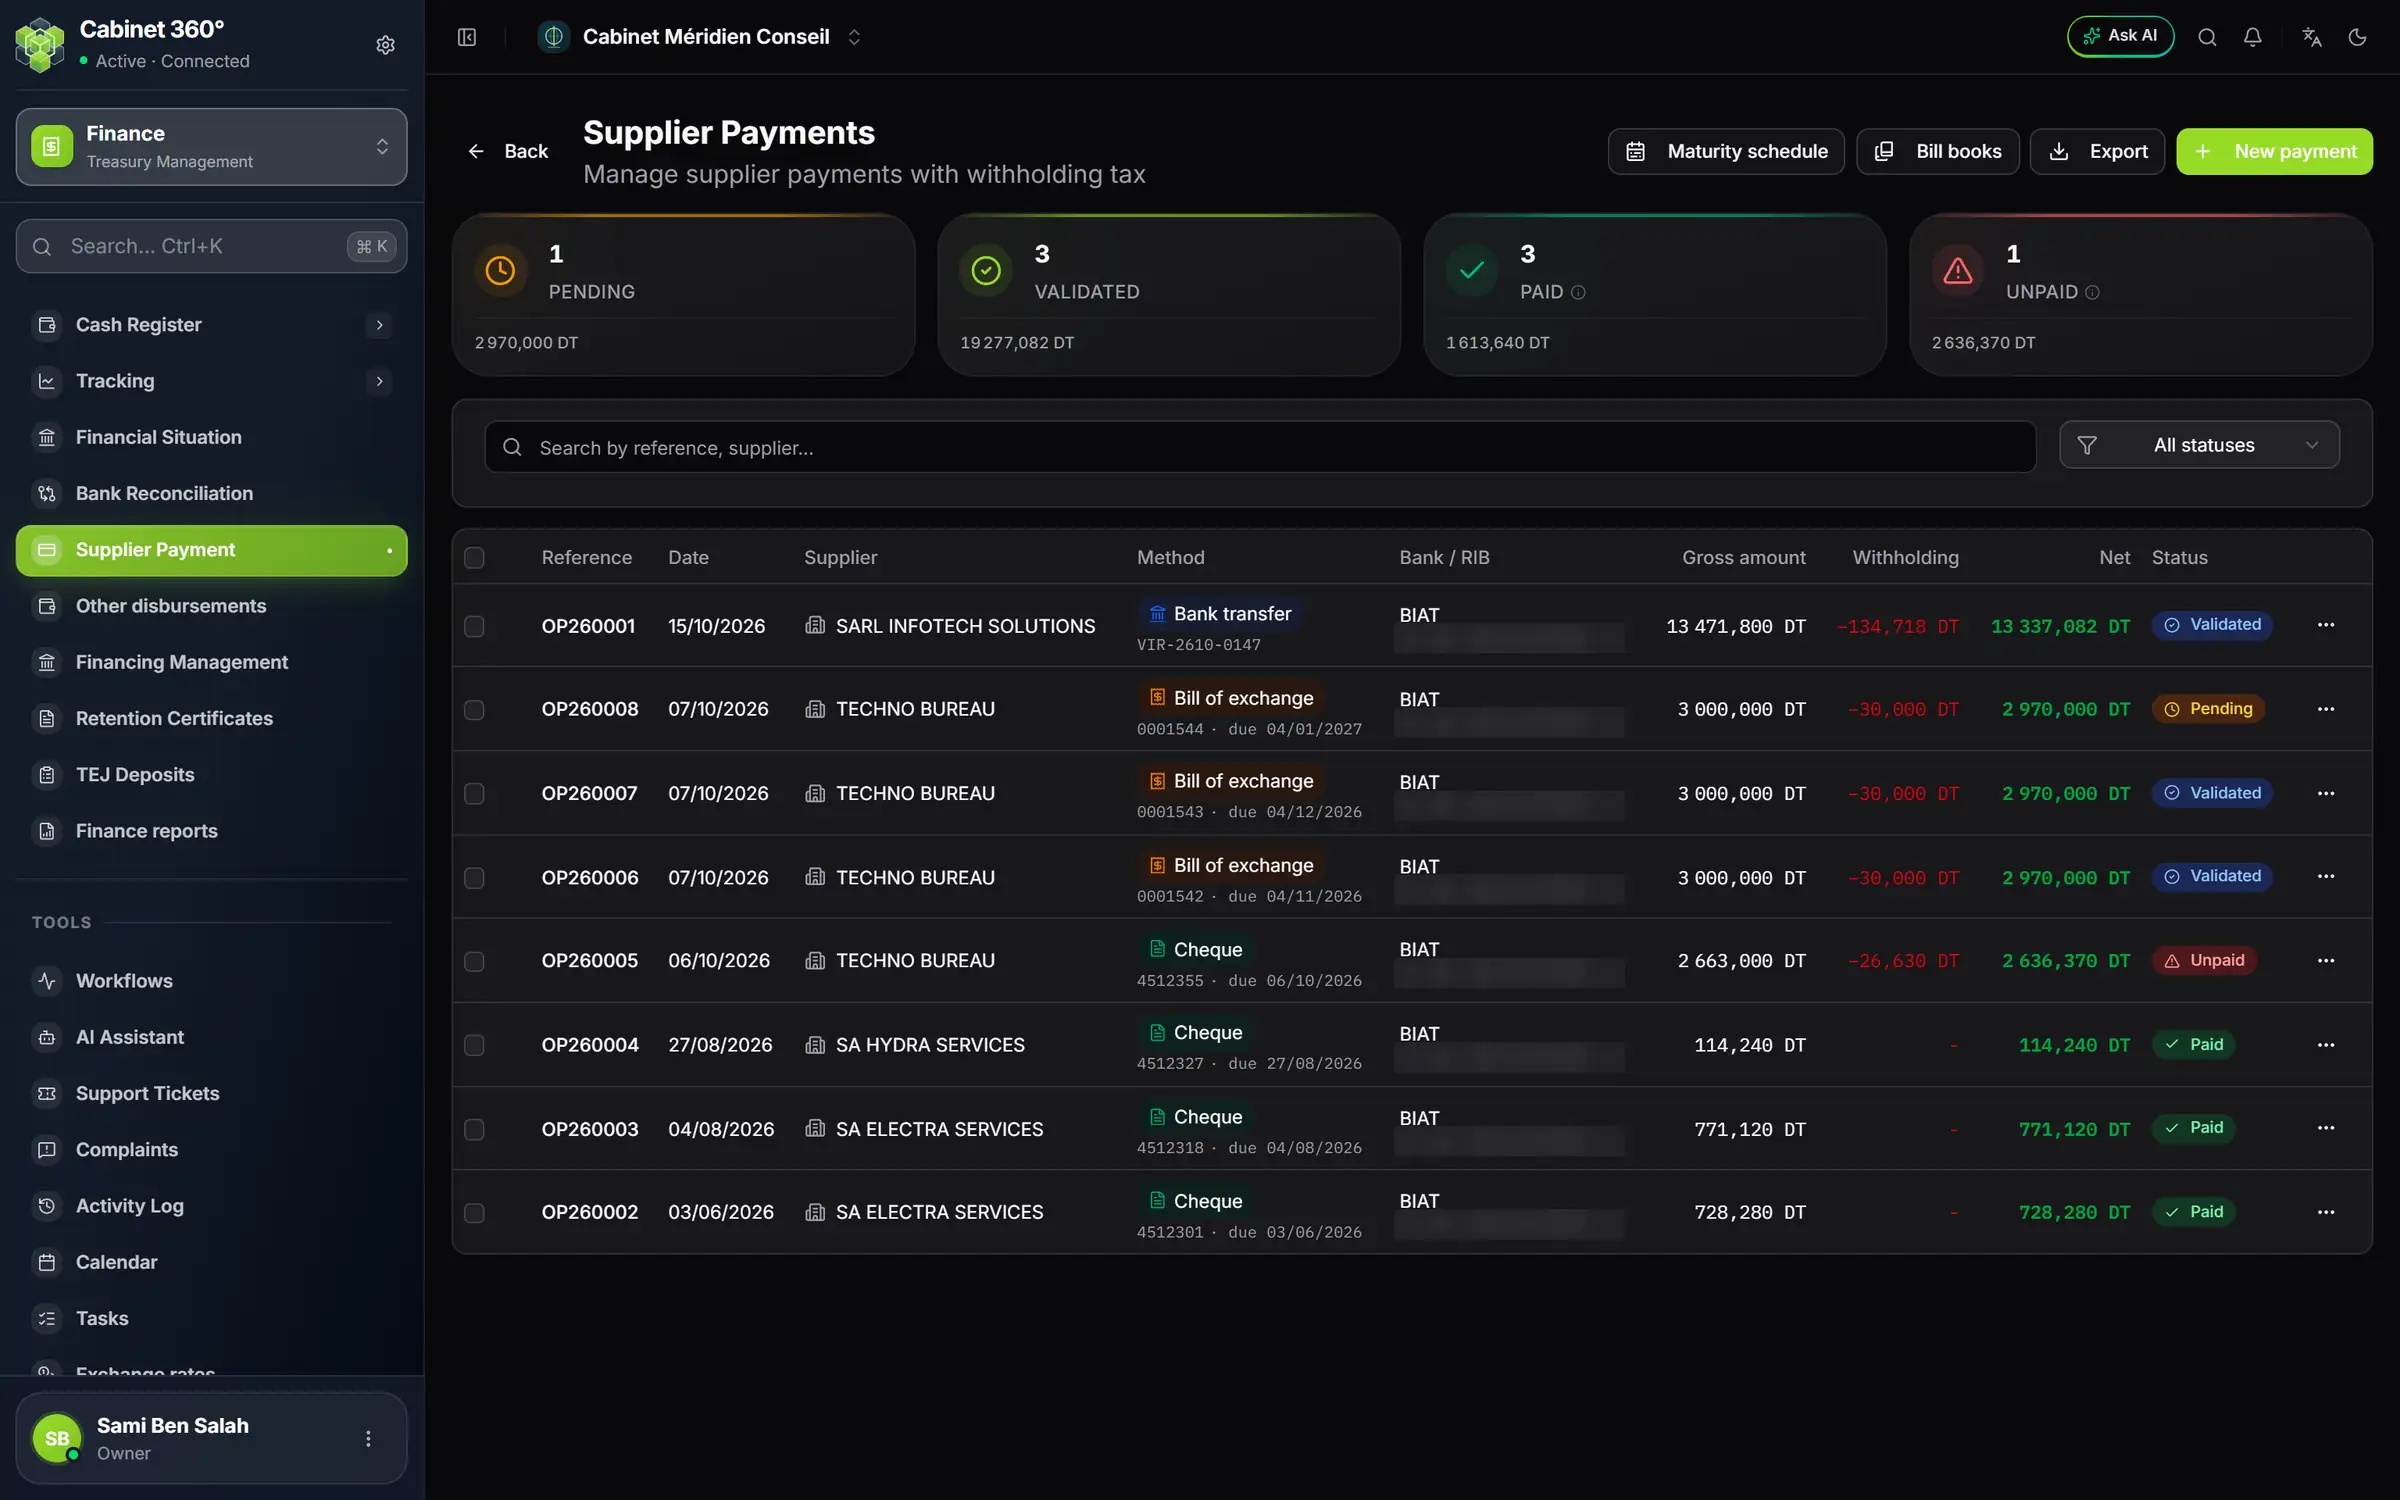
- 1. Maturity schedule, Bill books, Export, New payment.
- 2. The counters: pending, validated, paid, unpaid.
- 3. The method of each order.
- 4. The status: validated here, then paid or unpaid in Tracking › Disbursements.
What comes out
Print payment order gives the order on A4: beneficiary, settlement, allocation, gross, withholding, net, the amount in words and three approval boxes. Print bill fills the bill of a calibrated bill book, Print transfer the transfer order for the bank, and Send by email sends it to the supplier. Purchase documents print too: purchase order, receipt, supplier invoice, supplier credit note.